Low HOA Dues Can Hide a Big Special Assessment: What to Read Before Buying
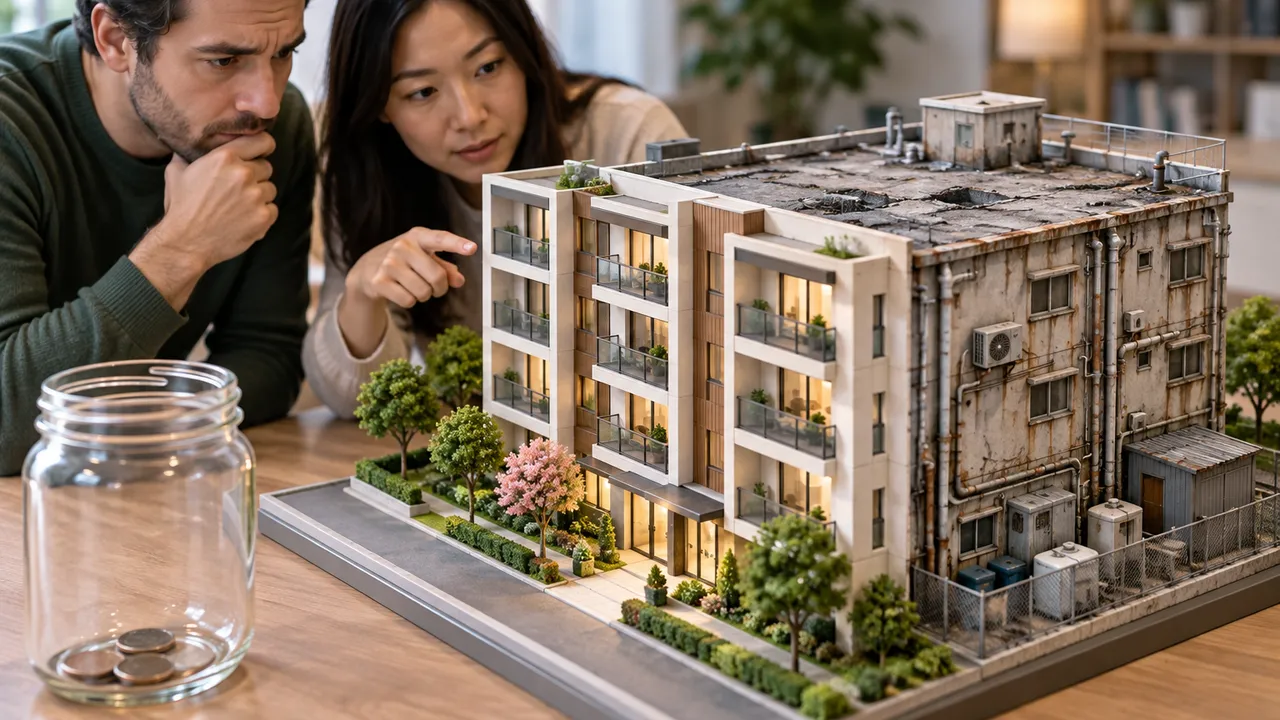
Low homeowners association dues can make a condo or planned-community home look affordable. But dues are only the monthly price tag. If an association has postponed repairs or underfunded reserves, owners may face a special assessment: an additional charge that can erase the apparent savings. Compare total ownership costs, including potential assessments, rather than advertised dues alone.
Before committing, read the association’s finances alongside its maintenance record and your purchase contract. As of October 2026, disclosure, inspection and reserve requirements vary by state and property type. A complete review should answer three questions: What needs work, how will it be funded, and who owes any pending charges?
1. Start with the reserve study, not the dues
A reserve study estimates when major shared components will need repair or replacement and how the association should save for them. Request the latest study, its underlying inspection date and any updates. Check whether it covers the actual property, including roofs, elevators, plumbing, roads and drainage where applicable.
Read the funding plan against the current reserve balance and scheduled contributions. “Percent funded” compares reserves with a benchmark tied to component wear; it is not a guarantee of solvency. A study can look reassuring while relying on outdated bids or repairs pushed beyond their useful lives.
Inspect the projected annual reserve balances for the next decade. A near-zero balance after roof replacement leaves little cushion if elevators fail earlier than expected.
| Study detail | What to check |
|---|---|
| Component inventory | Major shared assets are included |
| Cost estimates | Recent bids support replacement assumptions |
| Repair schedule | Urgent work is not postponed |
| Funding plan | Contributions match the adopted budget |
2. Test whether the budget supports the promises
Get the current operating budget, recent year-end financial statements, latest interim balance sheet and assessment delinquency totals. Compare actual spending with the budget. Repeated deficits, unpaid bills or transfers from reserves to cover routine expenses suggest that low dues are not sustainable. Check whether financial statements were audited, reviewed or compiled; those services provide different levels of assurance.
Ask the manager or treasurer to explain how approved projects will be financed. An association loan can reduce an immediate assessment but leave owners servicing debt through future dues. Large cash balances also mean little if the money is already committed.
Translate any funding shortfall into your unit’s potential share using the governing documents’ allocation formula. Equal division by the number of homes may be incorrect.
- Are scheduled reserve contributions actually being deposited?
- How much cash is unrestricted and available for repairs?
- Are utilities, insurance and maintenance costs rising faster than dues?
- Do delinquent owners leave paying owners covering a shortfall?
3. Use minutes to uncover delayed repairs
Request board and owner meeting minutes for roughly the past one to two years, plus engineering reports, inspection findings, maintenance logs and assessment notices. Minutes often reveal concerns before a formal charge appears: recurring leaks, failed inspections, contractor disputes or repeated votes to defer work.
Match those discussions to funded projects, signed contracts and completion dates. A fresh facade does not prove the roof or pipes are sound. If records mention structural concerns, obtain the engineer’s report and use an independent qualified professional to assess unresolved issues; a standard home inspection may not evaluate shared systems. Missing records are a reason to pause, not assume safety.
For work described as completed, request final inspection approvals, warranties and outstanding punch lists. Contractor payment alone does not establish that defects were corrected.
- Search for “special assessment,” “loan,” “water intrusion” and “deferred maintenance.”
- Request every notice, including proposed, approved and installment-based assessments.
- Ask what changed after the latest meeting minutes were prepared.
4. Check insurance gaps and owner exposure
Obtain the master insurance declarations, coverage summary and deductible schedule, then have an insurance professional review them. Identify property, flood, wind and other relevant coverage, exclusions and renewal dates. Some catastrophe deductibles are percentages rather than flat amounts; ask what insured value the percentage applies to and how that translates into dollars.
Determine whether the association can allocate a deductible or uninsured loss to individual owners under its governing documents and state law. Your condo unit policy, often called HO-6, may offer loss-assessment coverage, but limits, exclusions and deductible restrictions matter. It generally does not pay assessments for ordinary deterioration or planned capital work. Request a written coverage explanation and quote before removing contingencies, and ask how an insurance increase would affect next year’s budget. Do not treat that coverage as a substitute for healthy reserves.
Ask when the building’s replacement cost was last appraised. Coverage based on outdated construction prices can leave a rebuilding gap even when premiums are current.
5. Put responsibility for pending charges in writing
An assessment’s approval date, payment deadline and closing date can produce different obligations. Do not assume the seller pays because a board discussed the project before closing. Have your agent or real estate attorney identify the purchase contract’s allocation rules, then negotiate clear language covering approved assessments, installments and known proposals.
Request an updated resale disclosure package and association account statement shortly before closing. Where available, obtain an estoppel or status certificate showing charges against the property, and confirm its scope and effective date. A closing statement alone does not settle an ambiguous contract or eliminate association collection rights. Keep document-review and financing deadlines open long enough to evaluate new disclosures, or negotiate an extension before they expire.
If funds will be escrowed, specify who holds them, which invoices authorize release and when unused money returns to the seller. Obtain required lender approval.
- Specify whether the seller pays the entire assessment or only installments due before closing.
- Document any permitted credit or escrow, including responsibility for cost overruns.
- Have the lender confirm project eligibility; unresolved repairs or assessments can affect financing.
Verify current requirements through official state housing or condominium agencies, insurance departments and statutes; this is not personalized financial or legal advice.
AI Assistance Used — AI assistance was used in researching and drafting this article. It was reviewed, edited, and fact-checked by Leah Fornier before publication.