ABLE Accounts Expanded in 2026: Could You Save Without Losing SSI?
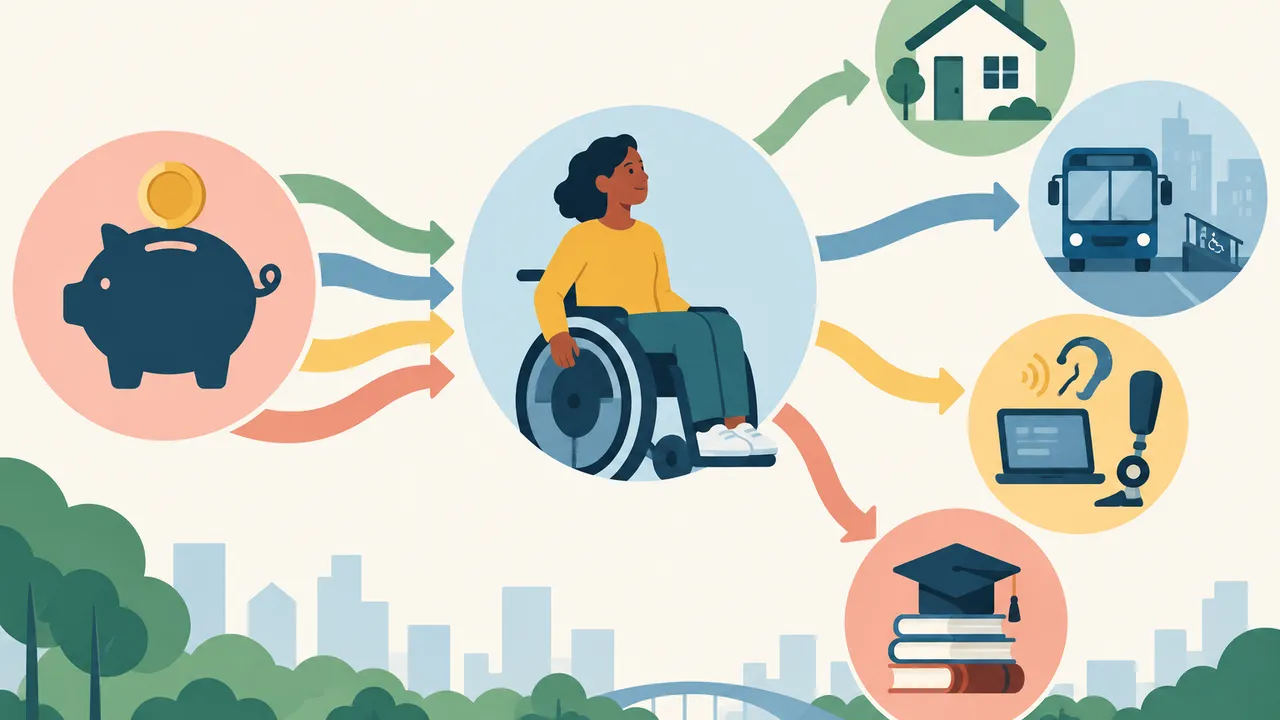
Adults whose disabilities began later in life gained a new savings option in 2026. Starting January 1, ABLE eligibility expanded to people whose qualifying disability began before age 46, replacing the previous before-age-26 requirement. The change can help people build financial reserves without automatically jeopardizing means-tested benefits. For newly eligible households, that could mean setting aside money for accessible equipment or a future move.
But an ABLE account is not an unrestricted shelter for money. Eligibility depends on when the disability began, contributions face limits, and withdrawals require care. Supplemental Security Income, or SSI, and Medicaid also apply different rules. Understanding those distinctions matters before moving savings.
1. The new rule concerns disability onset, not current age
You do not have to be younger than 46 when opening an account. Someone who is 60 may qualify if the disability began at 40. Conversely, a disability beginning at 46 generally misses the cutoff. A later diagnosis does not necessarily establish when the disabling condition began.
Receiving SSI or Social Security Disability Insurance based on a qualifying disability can establish eligibility, subject to the onset requirement. People not receiving those benefits may qualify through certification: qualifying blindness or a medically determinable impairment causing marked and severe functional limitations, expected to last at least 12 months or result in death.
If records are incomplete, ask your treating physician about earlier hospital reports, evaluations, or treatment notes documenting functional limitations. Evidence should support when the qualifying disability began, rather than merely when symptoms first appeared or benefits started.
- Document onset before the 46th birthday.
- Retain the required physician’s diagnosis for certification.
- Ask the ABLE program about its enrollment documentation.
2. Qualified expenses extend beyond medical bills
ABLE funds can pay qualified disability expenses connected to the beneficiary’s disability and supporting health, independence, or quality of life. That definition is broader than medical treatment: ordinary living expenses may qualify. Expenses do not necessarily need to be medically necessary or benefit only the person with a disability.
Keep receipts, invoices, and notes explaining the connection. Qualified withdrawals are federally tax-free; a nonqualified withdrawal can make its earnings portion taxable and generally trigger an additional 10% tax on those earnings. Housing deserves special attention because an otherwise qualified expense can create an SSI timing problem, discussed below.
For example, when paying for accessible transportation to work, save the ride receipt and record its purpose. Match each withdrawal to the associated expense in a simple ledger, especially when one withdrawal covers several purchases.
- Housing costs, including rent and utilities.
- Transportation and education.
- Assistive technology and personal support services.
- Health care, employment support, and financial management.
3. Contribution caps and balance limits are different
For planning, the standard annual contribution cap is around $20,000 in 2026; verify the exact current figure through the IRS and your plan. Contributions from the beneficiary, relatives, friends, and other sources generally share that cap. It is not a separate allowance for each donor.
Eligible employed beneficiaries may contribute additional earnings under ABLE to Work. That extra amount is limited to compensation or the applicable prior-year federal poverty amount, whichever is lower; Alaska and Hawaii have higher amounts. Contributions to certain employer retirement plans can prevent eligibility for this extra allowance that year.
Coordinate family gifts before year-end: a grandparent’s deposit uses the same annual allowance as your own savings. Track contributions across all sources, and ask the program how it handles excess deposits before scheduling an automatic transfer.
| Limit | What to verify |
|---|---|
| Standard annual contributions | IRS’s exact 2026 ABLE cap |
| ABLE to Work addition | Earnings, retirement contributions, and applicable poverty amount |
| State plan balance ceiling | Plan-specific aggregate limit, often several hundred thousand dollars |
| SSI balance exclusion | Separate $100,000 threshold, not a contribution cap |
4. SSI and Medicaid do not use identical rules
SSI generally excludes the first $100,000 in an ABLE account from countable resources. Amounts above that threshold count toward SSI’s ordinary resource limit, generally $2,000 for an individual. If excess ABLE funds alone cause ineligibility, cash payments are suspended, but Medicaid can continue while the person remains otherwise eligible.
Medicaid generally disregards ABLE balances, including amounts above $100,000. However, after the beneficiary dies, a state may seek repayment from remaining funds for Medicaid benefits paid after the account was established, subject to legal limits and permitted outstanding expenses. State recovery practices and protections vary; do not assume all remaining funds will reach heirs.
For example, rent money withdrawn on April 28 but held until May 1 generally becomes a countable resource in May. Arrange the withdrawal and payment within April, or wait until May to withdraw funds for May’s rent.
- Depositing wages into ABLE does not erase SSI income-counting rules.
- Spend housing withdrawals in the same calendar month; retained funds generally count as resources the next month.
- Keep nonhousing withdrawals identifiable and reserved for qualified expenses to preserve applicable exclusions.
5. Compare plans before moving money
You generally may choose an out-of-state ABLE program if it accepts nonresidents. Compare annual fees, investment costs, cash options, withdrawal processing times, and any home-state tax benefit. Investment accounts can lose value. Money needed soon for rent or transportation usually calls for a different approach than long-term savings.
Before enrolling, map expected deposits and spending against benefit rules. A benefits counselor can help distinguish SSI from SSDI, which has no asset limit, and review interactions with other assistance. For larger inheritances or complicated estate plans, ask an attorney familiar with disability benefits whether a special needs trust, an ABLE account, or both would better fit.
Check whether a plan’s cash option carries FDIC insurance and which bank holds deposits; investment portfolios generally do not have that protection. Also test whether its website, customer support, and payment tools meet your accessibility needs.
Current as of October 2026; verify rules with the IRS, Social Security, state Medicaid agency, and ABLE program; not personalized advice.
AI Assistance Used — AI assistance was used in researching and drafting this article. It was reviewed, edited, and fact-checked by Leah Fornier before publication.